How Financial Advisors and CPAs Work Together: Coordinating Tax and Wealth Planning
Many financial decisions have tax implications, and tax decisions can also affect your long-term financial plan. That's why coordination between your financial advisor and CPA matters. When these professionals work separately, opportunities may be missed, and recommendations may not always align.
There is more than one way to get that coordination. This article explains why it matters, the two common models for bringing tax and wealth planning together, and the decisions that benefit most when your financial advisor and CPA are on the same page.
Why Taxes and Wealth Planning Belong Together
Your CPA usually sees your finances once a year, looking backward at what already happened. Your financial advisor often looks forward, planning for goals years away. When the two perspectives are combined, you may get a clearer picture of both.
What Can Happen When They Work Separately
Surprise tax bills: An investment sale late in the year may create a tax bill your CPA did not expect.
Missed timing: Some planning ideas need to happen before year end, not at tax time.
Conflicting advice: One professional may recommend something the other would have cautioned against.
Duplicate work: You may end up gathering the same documents twice and explaining your situation repeatedly.
Two Approaches to Coordinating Tax and Wealth Planning
There are different ways financial advisors and tax professionals can coordinate their services. Two common approaches include working with an in-house tax team or collaborating with your existing CPA.
Model 1: In-House Tax Services
Some firms employ CPAs or tax preparers and offer tax services alongside investment management. This can be convenient, but it may mean changing CPAs if you already have one you trust.
Model 2: Collaboration With Your Own CPA
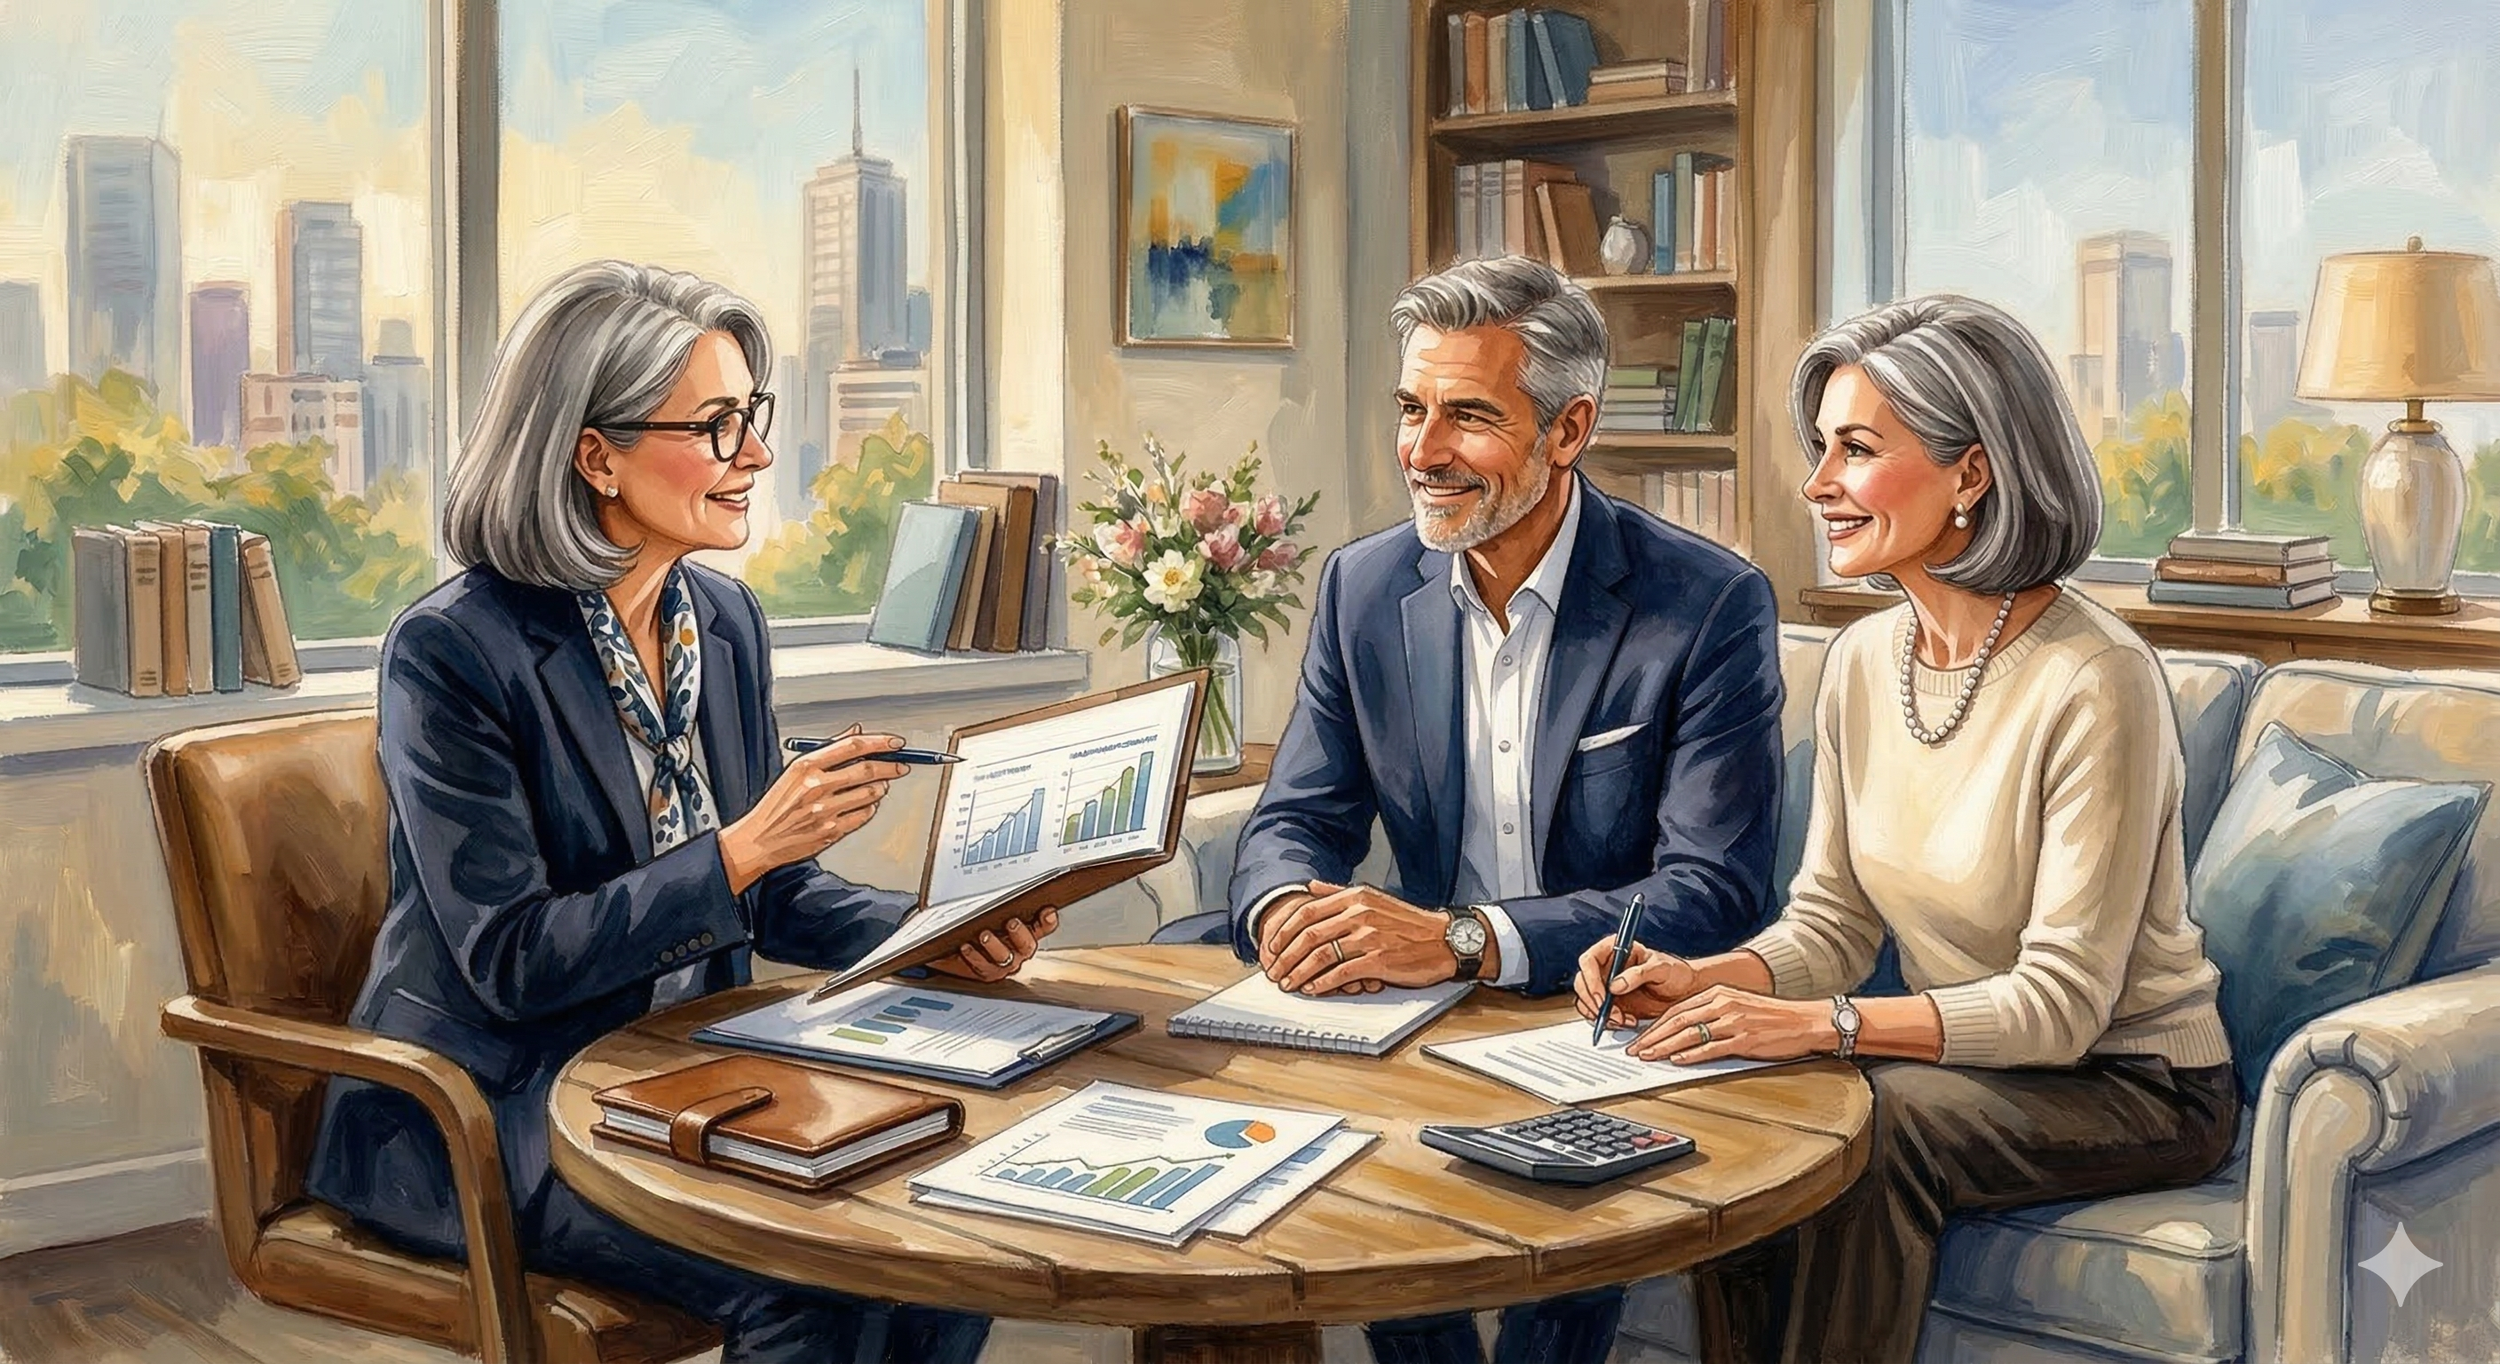
Other firms coordinate directly with the CPA and attorney you already use. You keep your existing relationships, and your advisors share information and plan together. This model can be a good fit for families who value their current professionals.
Questions to Help You Choose
Do I already have a CPA I want to keep?
Would I prefer one firm for everything, or a team that coordinates?
How will information be shared, and how often will everyone talk?
Who is responsible for which decisions?
Decisions That Benefit From Coordination
Here are areas where a financial advisor and CPA working together may make a real difference. Tax rules can change, so check current IRS guidance with your CPA.
Investment Decisions
Tax-aware investing: Considering which types of investments are held in taxable versus tax-deferred or tax-free accounts.
Realizing gains and losses: Timing sales with the full tax picture in mind.
Rebalancing: Choosing how and where to rebalance with taxes in view.
Retirement Decisions
Withdrawal order: Deciding which accounts to draw from first in retirement.
Required minimum distributions: Planning for distributions from certain retirement accounts once they apply.
Roth conversions: Weighing whether converting some savings may fit your plan, and when.
Charitable Giving
Giving strategies: Discussing approaches such as donating appreciated investments, donor advised funds, or qualified charitable distributions, where eligible.
Business Owner Decisions
Company retirement plans: Choosing among plan types with tax and business goals in mind.
Business sale or transition: Planning ahead for the tax effects of a sale or succession.
Estimated taxes: Coordinating cash flow with quarterly payments.
Estate Decisions
Beneficiary planning: Considering how different accounts may be taxed when inherited.
Gifting: Coordinating gifts to family with your attorney and CPA.
What Good Coordination Looks Like
Whichever model you choose, look for a few signs that coordination is real, not just a promise.
Shared information: Your advisor and CPA have access to the same key documents, with your permission.
Planning meetings: Professionals meet together, especially before year end.
Clear roles: Everyone knows who handles which tasks.
Follow-through: Action items are tracked and completed.
For a local look at how coordinated planning can work, read about wealth management and financial planning in Mansfield, Ohio.
How Pinnacle Advisors Approaches Tax Coordination
Pinnacle's mission is to "help individuals and families achieve financial success by providing comprehensive wealth management services in collaboration with their current advisors."
Wealth Collaboration™
Pinnacle follows the collaborative model. Through its Wealth Collaboration™ programs, Pinnacle brings your CPA and attorney to the table to provide holistic planning. Pinnacle is neither an attorney nor an accountant and does not provide legal or tax advice, which is why coordination with your own professionals is part of its approach.
Programs and Business Owner Services
Pinnacle's Wealth Management Programs include the Enhanced Wealth Management Program, specifically tailored to each business owner's story. The firm also offers retirement plans for small business owners, from SEP and SIMPLE IRAs to 401(k) and cash balance plans.
Who Pinnacle Advisors Serves and Where
Pinnacle works exclusively with individuals, business owners, and their families. The firm serves clients in Ohio, Florida, and across the nation, with its headquarters in Mansfield, Ohio, and offices in Mentor, Medina, and Columbus, Ohio; Sarasota/Bradenton and Tierra Verde, Florida; and Manhattan, Kansas.
Bring Your Advisors to the Table
If your CPA and financial advisor are not talking yet, a conversation can be a good first step. You can Schedule a Call, request a Free Assessment, or Download our eBook. Your needs lead the way. Start your snapshot.
Frequently Asked Questions
Should my financial advisor and CPA talk to each other?
Many families find it helpful. Coordination may help avoid surprise tax bills, improve timing, and keep investment and tax decisions aligned.
Is it better to have my taxes and investments at the same firm?
Not necessarily. Some people prefer one firm, while others keep their own CPA and choose an advisor who coordinates with them. Both models can work.
Can a financial advisor give tax advice?
It depends on the advisor. Many advisors, including those who are not CPAs, do not provide tax advice and instead coordinate with your CPA.
What is tax-aware investing?
Tax-aware investing considers the tax effects of investment decisions, such as where investments are held and when gains or losses are realized.
When should my CPA and financial advisor meet?
Before year end is often helpful, since some planning decisions must be made before December 31. Meeting before major events, like a business sale, can also help.
How do I get my CPA and financial advisor to work together?
Give both professionals permission to share information, ask your advisor how they coordinate, and consider scheduling a joint planning meeting.
This article is for educational and informational purposes only and should not be construed as personalized investment, legal, accounting, or tax advice. Pinnacle Advisors is an SEC registered investment adviser located in Mansfield, Ohio. The Company is neither an attorney nor an accountant, and no portion of this content should be interpreted as legal, accounting or tax advice. It should not be assumed that future performance of any specific investment or investment strategy or any planning or consulting services will be profitable, equal any historical performance level(s), or prove successful if Pinnacle is engaged. Investing involves risk, including the possible loss of principal, and there are no guarantees that any strategy will achieve its objectives. Please review the Important Disclosure Information and Form CRS available on the Company's website.








IMPORTANT DISCLOSURE INFORMATION
Please remember that past performance is no guarantee of future results. Different types of investments involve varying degrees of risk, and there can be no assurance that the future performance of any specific investment, investment strategy, or product (including the investments and/or investment strategies recommended or undertaken by Pinnacle Advisors [“Pinnacle”]), or any non-investment related content, made reference to directly or indirectly in this blog will be profitable, equal any corresponding indicated historical performance level(s), be suitable for your portfolio or individual situation, or prove successful. Due to various factors, including changing market conditions and/or applicable laws, the content may no longer be reflective of current opinions or positions. Moreover, you should not assume that any discussion or information contained in this blog serves as the receipt of, or as a substitute for, personalized investment advice from Pinnacle. To the extent that a reader has any questions regarding the applicability of any specific issue discussed above to his/her individual situation, he/she is encouraged to consult with the professional advisor of his/her choosing. No amount of prior experience or success should be construed that a certain level of results or satisfaction will be achieved if Pinnacle is engaged, or continues to be engaged, to provide investment advisory services. Pinnacle is neither a law firm nor a certified public accounting firm and no portion of the blog content should be construed as legal or accounting advice. A copy of the Pinnacle’s current written disclosure Brochure discussing our advisory services and fees is available for review upon request or at www.pinnacleadvisors.com. Please Note: Pinnacle does not make any representations or warranties as to the accuracy, timeliness, suitability, completeness, or relevance of any information prepared by any unaffiliated third party, whether linked to Pinnacle’s web site or blog or incorporated herein, and takes no responsibility for any such content. All such information is provided solely for convenience purposes only and all users thereof should be guided accordingly. Please Remember: If you are a Pinnacle client, please contact Pinnacle, in writing, if there are any changes in your personal/financial situation or investment objectives for the purpose of reviewing/evaluating/revising our previous recommendations and/or services, or if you would like to impose, add, or to modify any reasonable restrictions to our investment advisory services. Unless, and until, you notify us, in writing, to the contrary, we shall continue to provide services as we do currently. Please Also Remember to advise us if you have not been receiving account statements (at least quarterly) from the account custodian.
Financial advisor Ohio, financial advisor Florida, financial planner Ohio, financial planner Florida, wealth management Ohio, wealth management Florida, financial coach Ohio, financial coach Florida, retirement planning Ohio, retirement planning Florida, investment planning Ohio, investment planning Florida, wealth planning Ohio, wealth planning Florida, financial expert Ohio, financial expert Florida, wealth strategist Ohio, wealth strategist Florida, wealth coordinator Ohio, wealth coordinator Florida, wealth planning specialist Ohio, wealth planning specialist Florida, investment planner Ohio, investment planner Florida, exit plan Ohio, exit plan Florida, trust services Ohio, trust services Florida, CFP Ohio, CFP Florida, money manager Ohio, money manger Florida, boutique wealth management Ohio, boutique wealth management Florida, boutique money manager Ohio, boutique money manager Florida
